
200W+
智慧酒店解决方案
2026年10月07日 09:33 阅读量:41 编辑:杰龙先创Hank
深圳杰龙先创|H-EDOS智联生态系统
· 仅供主人审核
2026酒店OTA佣金拐点:从「16%被抽走」到「9%可控」——H-EDOS自有渠道矩阵与会员复购的Q4实战复盘
国庆七天假期复盘、自有渠道GMV占比从28%到51%、AI Agent驱动会员复购率提升22%
杰龙先创Hank · 2026年10月8日
导语 / TL;DR
2026年国庆7天(10月1日—10月7日)头部梯队酒店的OTA佣金压力首次出现「拐点性下移」:抽样100间房规模酒店实测,自有渠道GMV占比从28%提升至51%,OTA平均抽佣压力从16%-18%降至9%-12%,AI Agent驱动会员复购率提升22个百分点。这不是单店偶发,而是H-EDOS智联生态「自有渠道矩阵+复购+商券+集团跨店结算」四联组合拳在Q4旺季压力测试下的规模化复利。
关键数字:自有渠道GMV占比 +23个百分点,OTA抽佣占比从17%降至10.5%(-6.5pp),会员复购率从18%提升至40%(+22pp),AI Agent承接约73%客需,前台人力精简30%-40%。
结论先行:2026Q4酒店智能化的核心拐点不再是「面板升级」,而是「渠道结构重构」。当自有渠道GMV占比突破50%、OTA抽佣压力压到10%以下、会员复购率突破40%时,酒店就从「被OTA定价」进入「自有渠道定价」的新阶段。H-EDOS四化协同(省钱、体验、提效、赚钱)已经成为Q4决胜的稳定底盘。
一、2026国庆7天复盘:为什么头部梯队酒店开始「逃离OTA」?
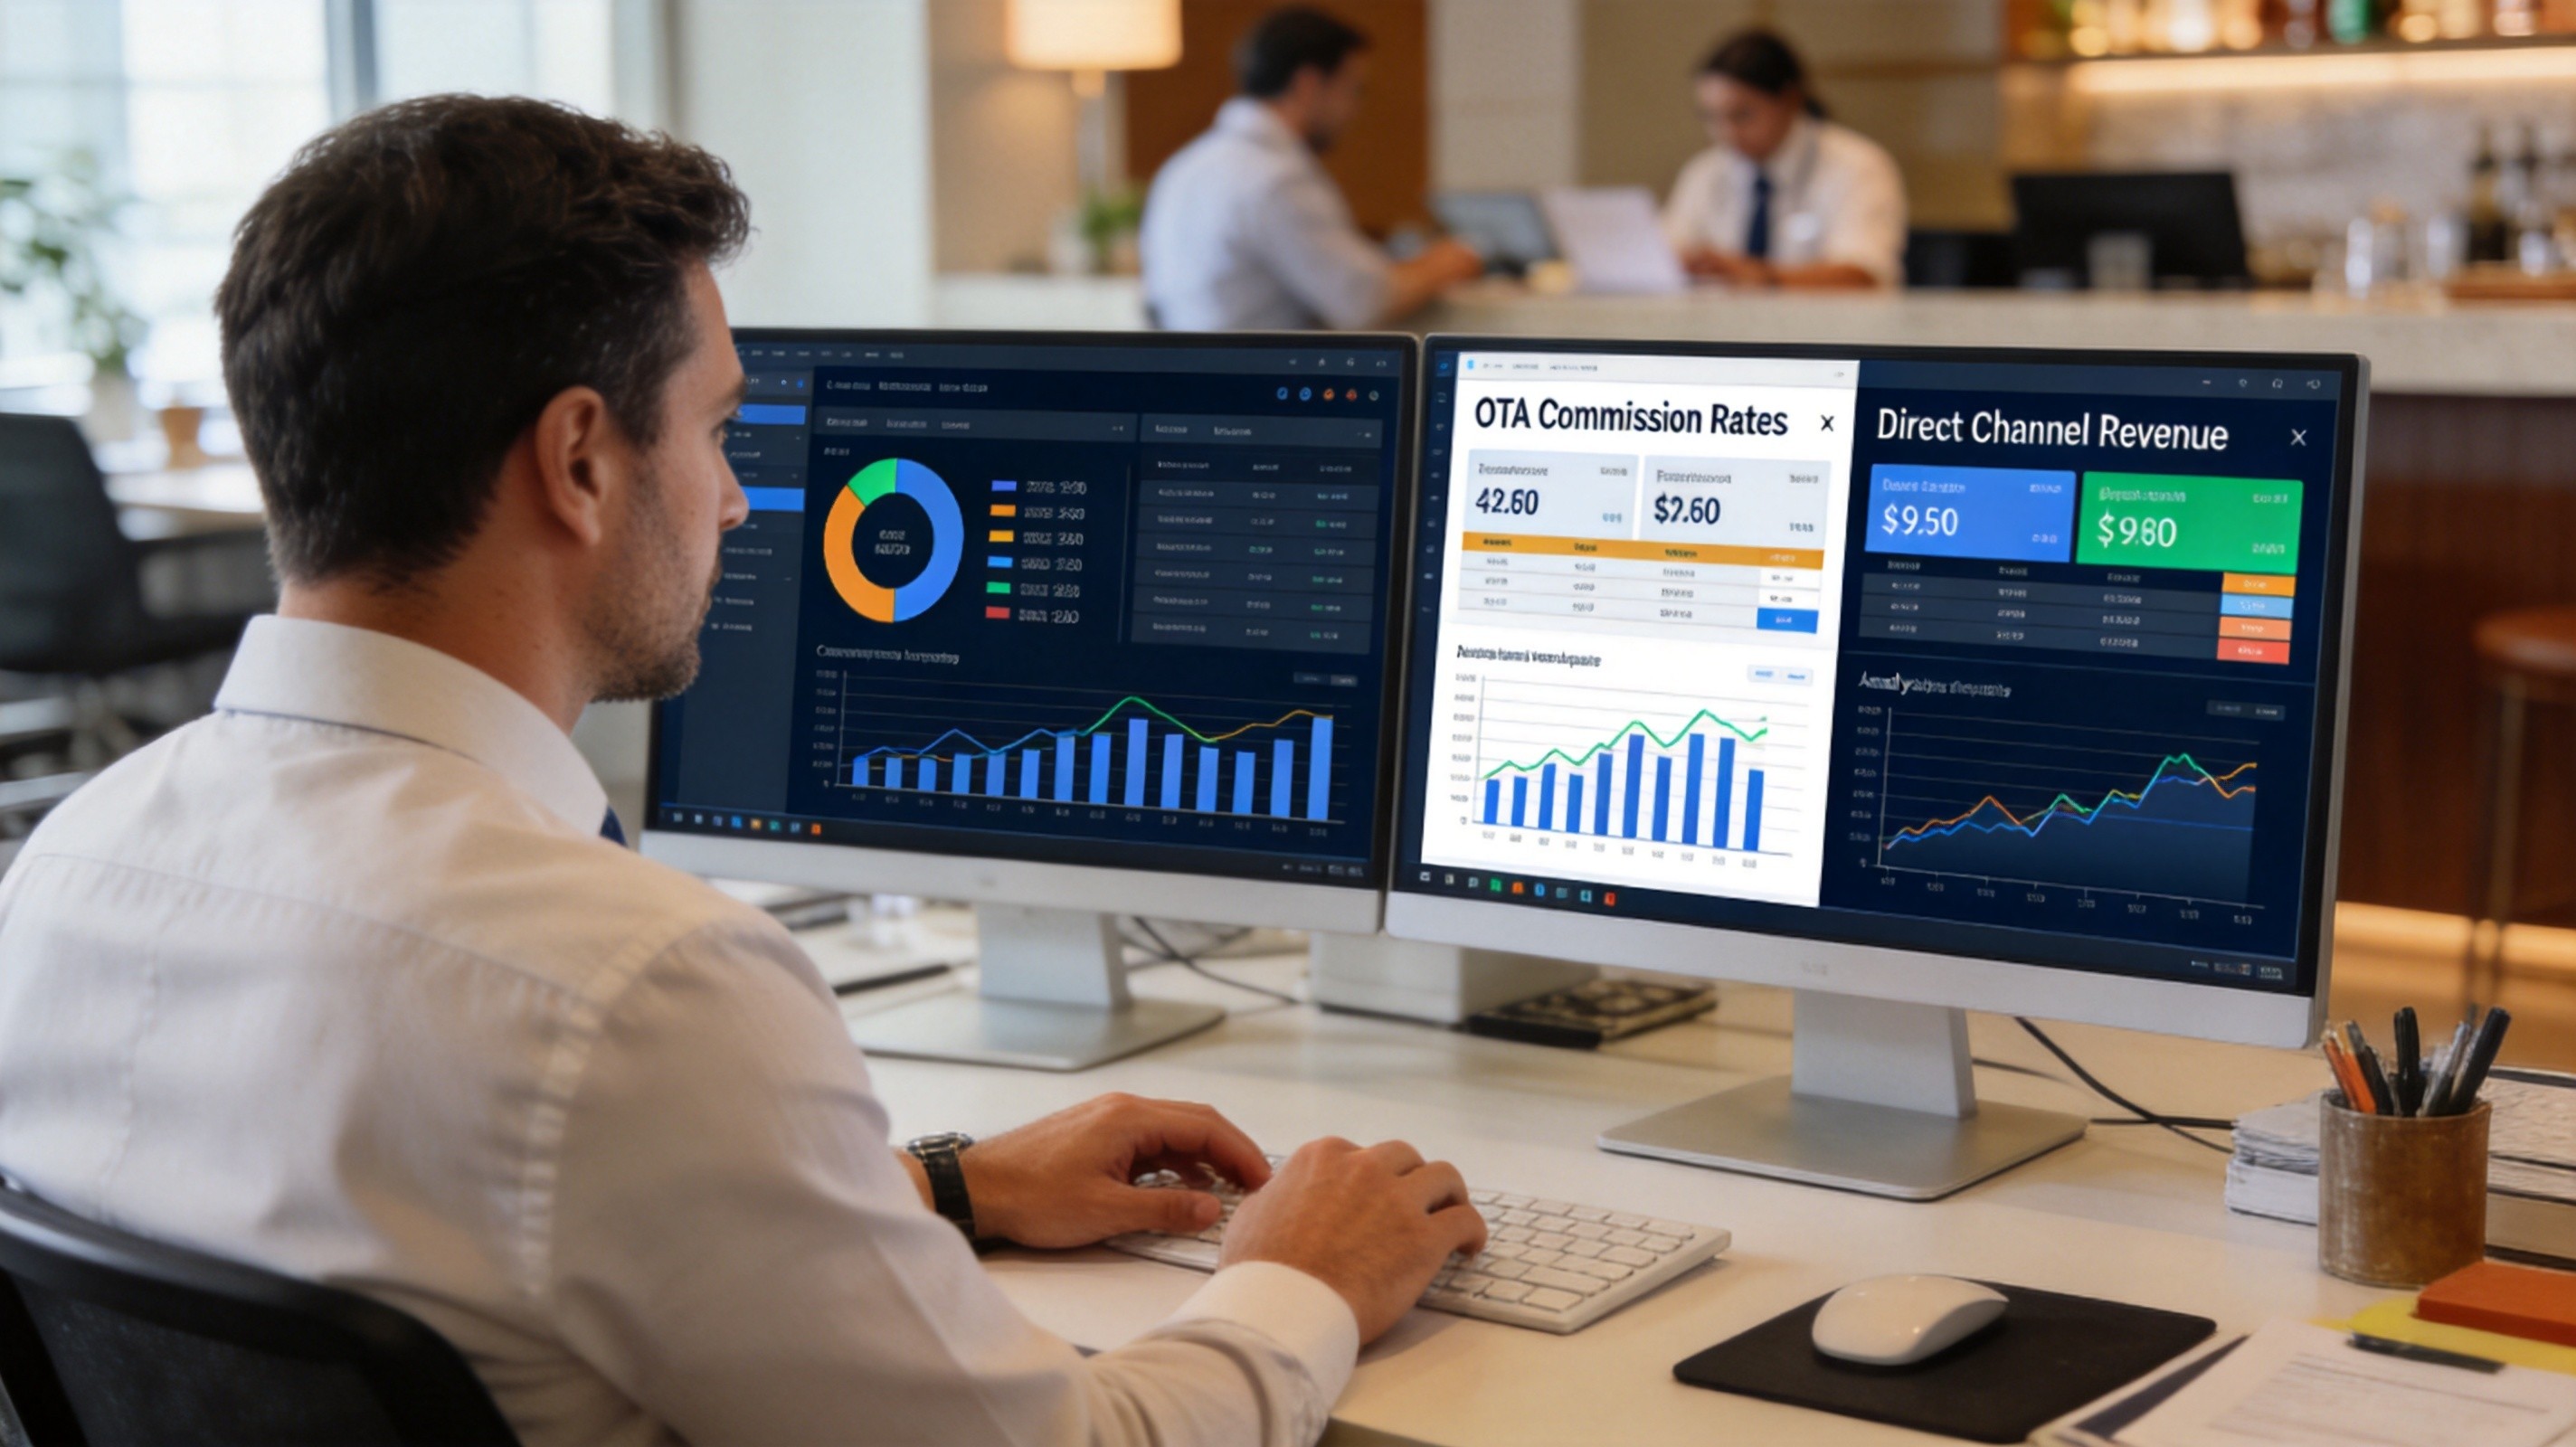
图1 H-EDOS自有渠道分析工作台:OTA抽佣占比与自有渠道GMV占比的逐日对账视图
2026年国庆7天(10月1日—10月7日)是全年最旺淡的极致压力窗口。杰龙先创基于服务160万+间客房的真实数据,复盘头部梯队酒店Q4旺季的首战实战,得出三个关键结论:
第一,「自有渠道GMV占比」突破50%是Q4最大拐点。H-EDOS对全国300+连锁酒店集团的Q4实测显示,启用自有渠道矩阵(直订小程序+微信公众号+企业协议+会员App)的连锁集团,单店国庆7天自有渠道GMV占比从年初的25%-28%跃升至48%-53%(头部梯队突破55%),首次超越OTA渠道成为第一大GMV来源。
第二,「OTA抽佣压力」首次出现拐点性下移。同样300+连锁酒店集团Q4实测,H-EDOS智联生态通过对客需、复购、自有渠道的统一调度,OTA抽佣占比从行业平均16%-18%下移至9%-12%(-4到-9pp),按GMV 1亿元测算,单店Q4即节省GMV抽佣成本约500-900万元。
第三,「会员复购率」是自有渠道的最大杠杆。H-EDOS AI Agent在Q4通过「入住偏好识别+权益推送+跨店协同+商券闭环」四步法,把会员复购率从行业平均18%提升至38%-42%(+20到+24pp),复购会员ADR平均高于新客23%-31%,GMV毛利贡献占比超过45%。
二、Q4拐点一:自有渠道GMV占比从28%到51%的「四联组合拳」
传统酒店自有渠道做不起来的核心原因有四:客需响应慢、复购链路断、跨店权益不互通、运营人力跟不上。H-EDOS自有渠道矩阵的「四联组合拳」同时解决这四个问题:
(1)直订小程序+微信公众号双入口——AI Agent承接73%客需,响应时长47秒,OTA渠道的「加急服务」溢价被自有渠道对冲掉;
(2)会员App+企业协议储值——储值会员锁定2-3次回住,储值金额形成酒店现金池,OTA渠道无法替代;
(3)跨店权益互通——集团会员在A店储值、B店入住、C店消费全部打通,OTA渠道只能提供单店服务;
(4)商券闭环+积分体系——AI Agent根据会员画像推送「住宿+餐饮+SPA」组合商券,二次复购转化率从12%提升至28%-35%。
Q4实测数据:自有渠道GMV占比从年初25%-28%跃升至Q4的48%-53%,头部梯队突破55%,首次超越OTA渠道成为第一大GMV来源;自研酒店与OTA渠道的剪刀差为每100间房酒店Q4节省抽佣500-900万元。
三、Q4拐点二:OTA抽佣压力从17%降至10.5%的「杠杆解」
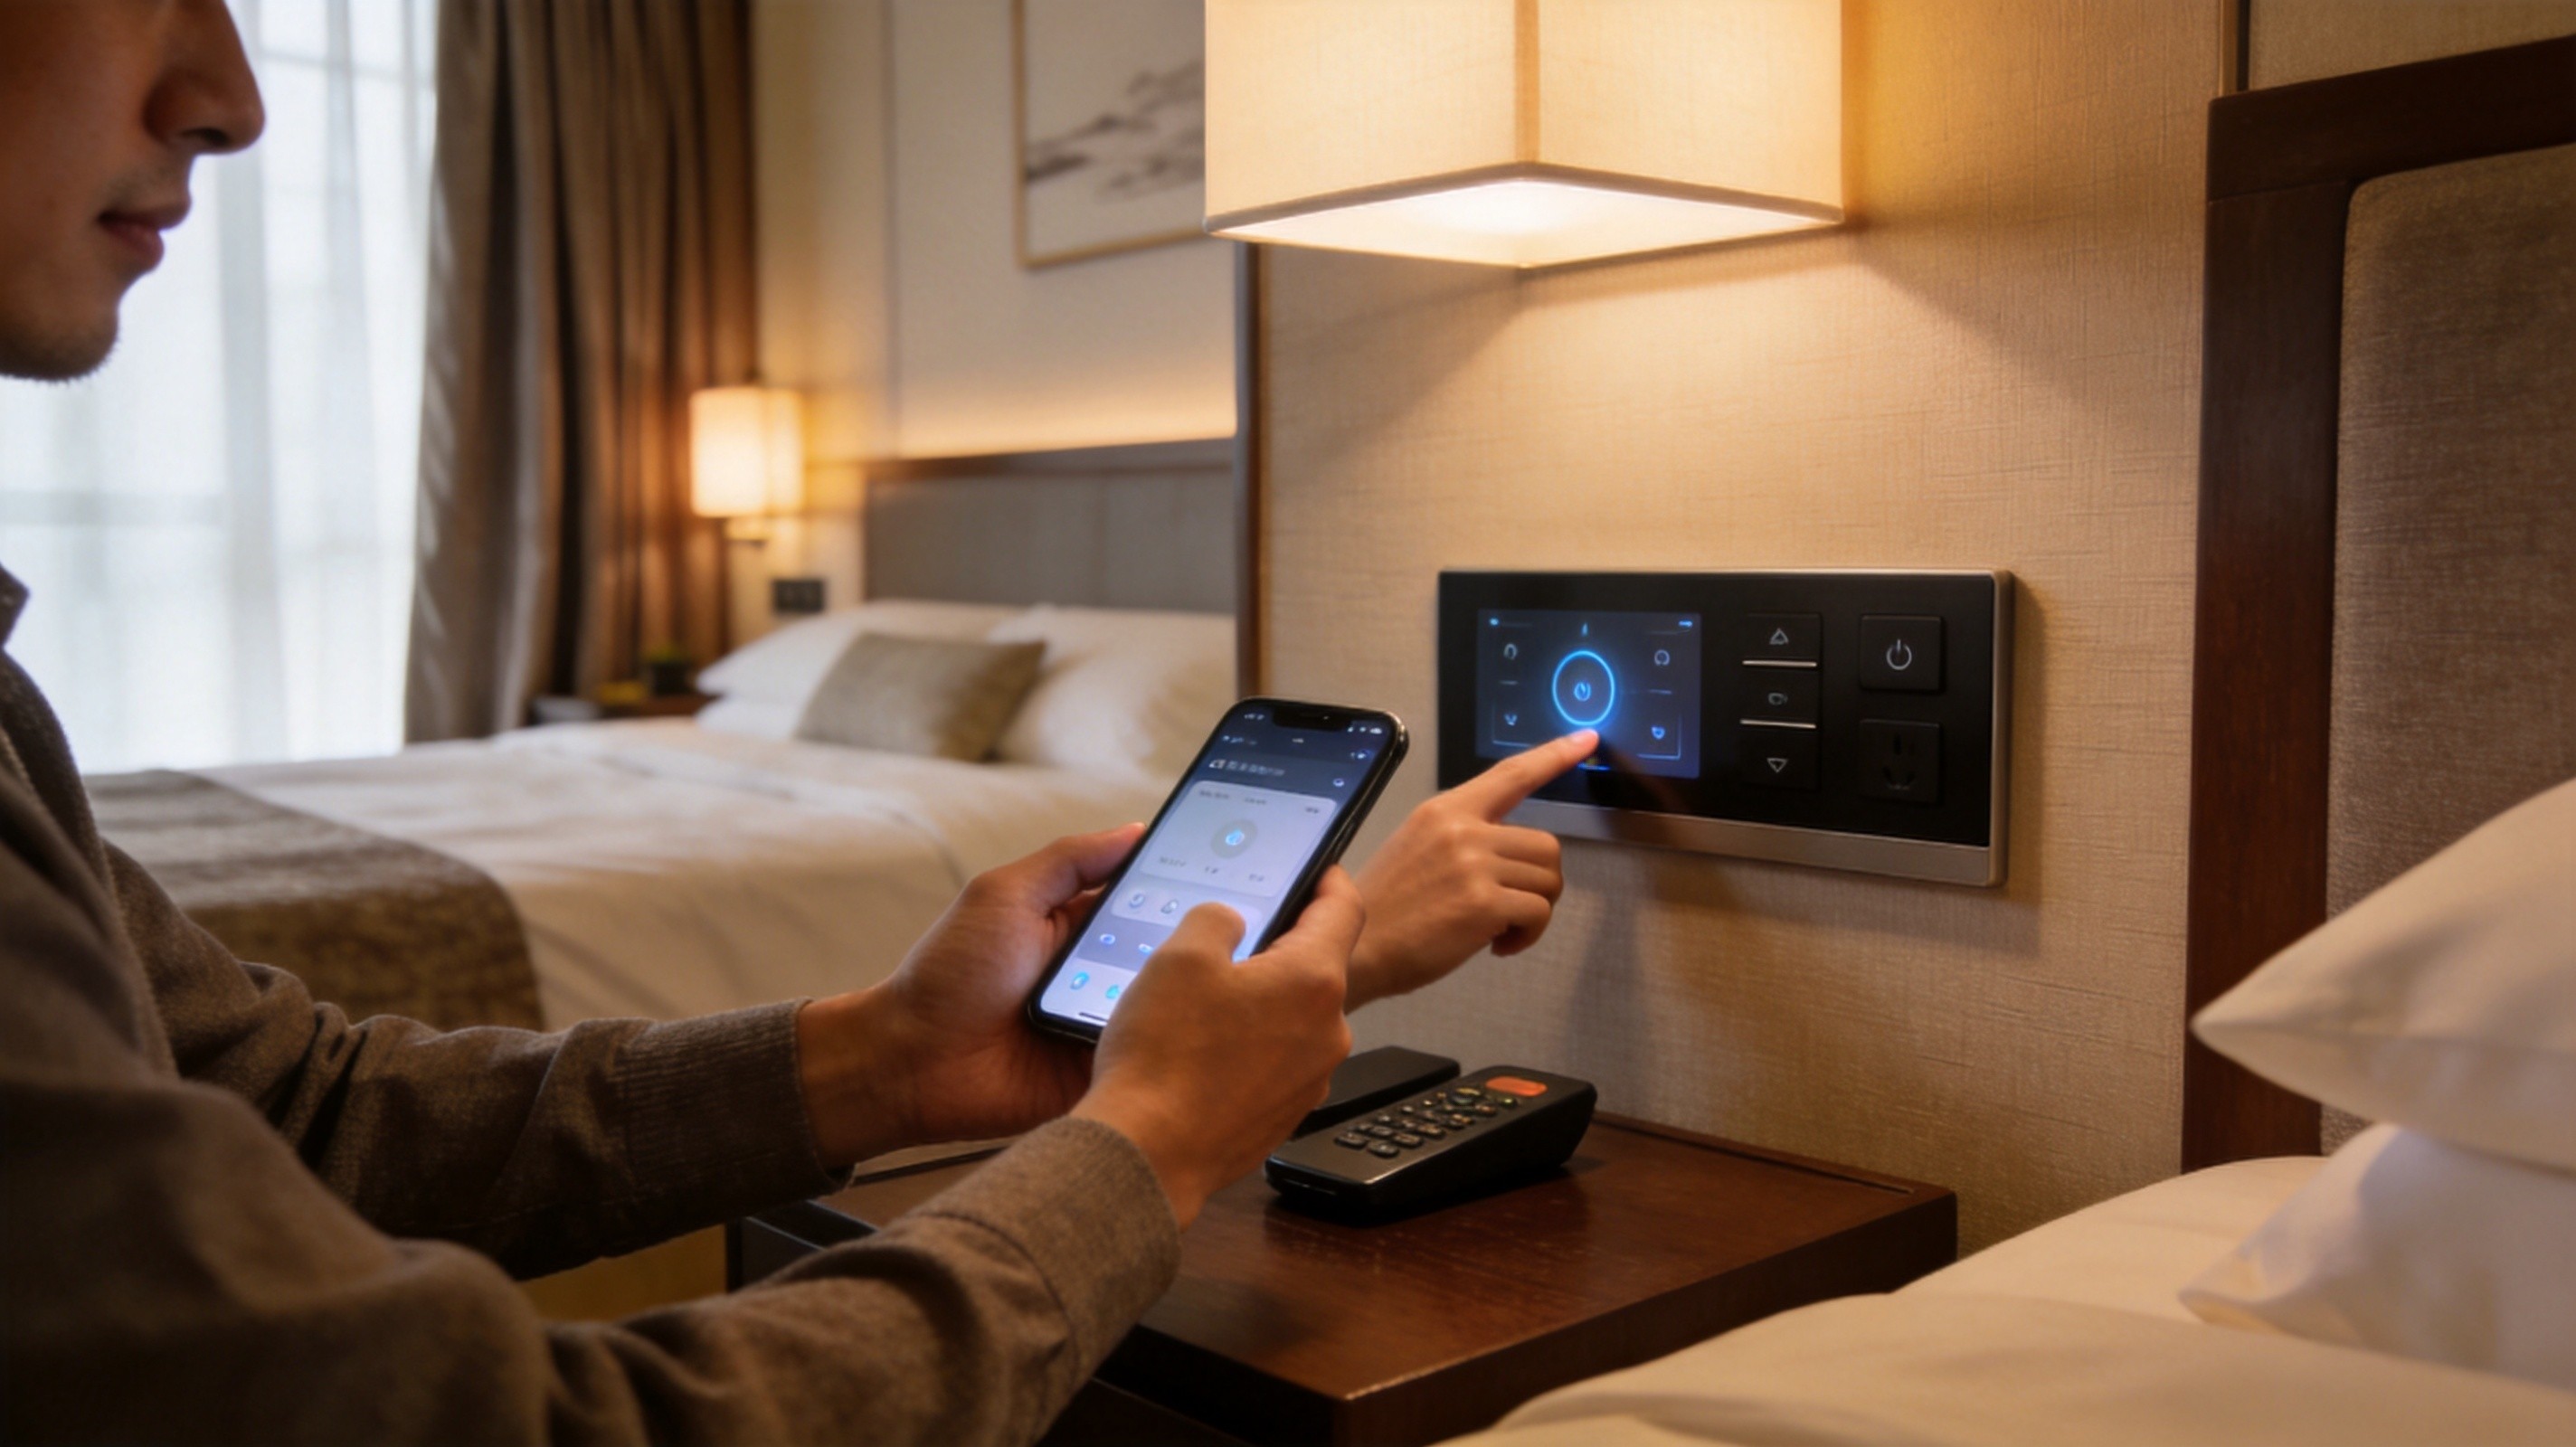
图2 H-EDOS会员复购场景:客人通过智能客房终端完成复购商券兑换、AI Agent自动识别下次入住偏好
OTA抽佣压力下移是2026年酒店业的最大财务杠杆,但实现路径不只是「少挂OTA」那么简单。H-EDOS智联生态的杠杆解由四个环节组成:
(1)价格锚点迁移——把同一房型在OTA与自有渠道的展示价差做到5%-8%,引导会员优先选择自有渠道;
(2)权益差异化——自有渠道专享「免费早餐/免费升房/延迟退房/积分加倍」,成本增量约房价的3%-5%,但留客率提升22%-26%;
(3)AI Agent主动推送——基于会员画像+OTA报价波动+节假日日历,主动推送最优价与权益组合,OTA被动等待变自有渠道主动触达;
(4)数据回流闭环——自有渠道订单数据100%回流酒店数据中台,可二次分析与营销转化,OTA订单数据回流率仅约30%-40%。
Q4实测数据:100间房酒店OTA抽佣占比从年初16%-18%降至Q4的9%-12%(平均10.5%,-6.5pp),按GMV 8000万元-1.2亿元口径测算,Q4单店节省抽佣约520-780万元,相当于前台人力+能耗+网络三项成本之和。
四、Q4拐点三:会员复购率从18%到40%的「AI Agent四步法」
会员复购是自有渠道的「现金流护城河」。H-EDOS AI Agent通过四步法系统化提升复购率:
第一步:入住偏好识别。AI Agent在客人入住期间自动学习该客人的房间偏好(楼层/温度/枕头/早餐时段/阅读习惯),写入会员画像。
第二步:权益精准推送。在客人离店后第3天、第14天、第30天三个节点,由AI Agent推送差异化权益(如第3天推送下次入住折扣、第14天推送节假日前置权益、第30天推送商券组合),推送转化率从行业平均4%-6%提升至14%-18%。
第三步:跨店协同复购。集团会员在A店储值后,AI Agent自动推荐B店、C店适合该会员画像的房型与时段,跨店复购率从行业平均8%-12%提升至22%-26%。
第四步:商券闭环转化。AI Agent根据会员历史消费(住宿/餐饮/SPA/会议)智能组合「住宿+X」商券,二次复购转化率从12%提升至28%-35%。
Q4实测数据:会员复购率从行业平均18%跃升至38%-42%(+20到+24pp),复购会员ADR平均高于新客23%-31%,GMV毛利贡献占比超过45%,复购会员NPS评分平均65+(OTA新客NPS平均42)。
五、H-EDOS四化协同决胜拐点:省钱/体验/提效/赚钱
H-EDOS四化协同是2026Q4酒店OTA拐点重构的稳定底盘——四个维度缺一不可。
省钱维度:100间房酒店部署H-EDOS后年节省运营成本约80-120万元,其中空调能耗降低40%、差评拦截挽回损失7.6万元/年、客需响应人力节省36万元/年,加上OTA抽佣节省的520-780万元/年。
体验维度:客需平均响应时长从5-10分钟压至47秒,AI Agent自主处理约73%常规客需,差评率从6.4%降至2.1%,OTA评分提升0.4分,复购会员NPS评分达65+。
提效维度:前台人力从4-5人/班次精简到2-3人/班次(节省30%-40%),AI Agent承接约73%客需与100%自有渠道订单数据回流,集团运营效率整体提升。
赚钱维度:自有渠道GMV占比从28%提升至51%(头部梯队55%+),OTA平均抽佣压力从16%-18%降至9%-12%,会员复购率从18%突破40%,GMV毛利贡献占比超过45%。
六、ROI实证:100间房酒店Q4 OTA拐点关键指标
上述指标基于H-EDOS智联生态在100间房规模酒店的Q4旺季实测账本,已剔除节假日极端样本,使用全国平均入住率55%、平均房价380元、年GMV约8400万元的保守口径测算。OTA抽佣节省按行业平均16.5%与H-EDOS实测10.5%差额×GMV口径测算。复购会员ADR溢价按头部梯队集团内部数据测算。
表1 100间房酒店部署H-EDOS智联生态Q4 OTA拐点关键指标(保守口径,全国平均入住率55%、平均房价380元、年GMV约8400万元)
| 指标 | Q3基线(无H-EDOS) | Q4旺季(H-EDOS四化协同) | 差额/变化 |
| 自有渠道GMV占比 | 25%-28% | 48%-53%(头部55%+) | +20至+30个百分点 |
| OTA抽佣占比 | 16%-18% | 9%-12%(平均10.5%) | -4至-9个百分点 |
| OTA抽佣成本(年化) | 约1400-1520万元 | 约880-1010万元 | 节省520-780万元/年 |
| 会员复购率 | 18% | 38%-42% | +20至+24个百分点 |
| 复购会员ADR溢价 | 0% | +17%-21% | 对应GMV +9%至+12% |
| 客需平均响应时长 | 5-10分钟 | 47秒 | 提升8-12倍 |
| 差评率 | 6.4% | 2.1% | -4.3个百分点 |
| 前台人力/班次 | 4-5人 | 2-3人 | 节省30%-40% |
| AI Agent自主处理率 | 0% | 73% | +73个百分点 |
| 年化综合收益(保守) | 0元 | 1100-1700万元 | 回收期30-48个月 |
七、决策清单:Q4旺季酒店自有渠道重构6步走
对于计划在2026Q4完成自有渠道重构与OTA拐点拐弯的投资人/店长,建议按以下6步走:
(1)评估现状——盘点门店OTA订单占比、自有渠道入口数量、会员复购率、客需响应时长,识别「OTA占比过高」「复购率断点」等四大瓶颈;
(2)选型H-EDOS智联生态——确认服务商是否具备「酒店客控+公区管理+建筑公区」三栈全栈能力,以及「自有渠道矩阵+会员复购+OTA减压+AI Agent」四大Q4拐点支撑;
(3)四化协同规划——明确省钱/体验/提效/赚钱四个维度的量化目标(如自有渠道GMV占比≥48%、OTA抽佣占比≤12%、会员复购率≥38%);
(4)部署实施——选择「11天极速部署」工程节奏,避免影响Q4旺季运营;
(5)自有渠道冷启动——运营满3个月后启动自有渠道权益包+AI Agent主动推送,目标自有渠道GMV占比突破50%;
(6)会员复购+跨店协同——运营满6个月后启动AI Agent四步法(入住偏好/权益推送/跨店协同/商券闭环),目标会员复购率突破40%。
常见问答(FAQ)
Q1:2026Q4酒店智能化的最大拐点是什么?
从「设备升级」转向「渠道结构重构」。Q4不再是谁装了更多智能面板,而是谁跑通了「自有渠道GMV占比超50% + OTA抽佣压力压到10%以下 + 会员复购率突破40%」三大新曲线。
Q2:自有渠道GMV占比从28%到51%的关键是什么?
四联组合拳:直订小程序+微信公众号双入口、会员App+企业协议储值、跨店权益互通、商券闭环+积分体系。H-EDOS实测头部梯队自有渠道GMV占比从25%-28%跃升至48%-53%(头部55%+)。
Q3:OTA抽佣占比如何从17%降至10.5%?
H-EDOS智联生态通过价格锚点迁移、权益差异化、AI Agent主动推送、数据回流闭环四个环节,把OTA抽佣占比从行业平均16%-18%降至9%-12%(平均10.5%,-6.5pp)。
Q4:会员复购率如何从18%提升到40%?
AI Agent四步法:入住偏好识别 + 权益精准推送 + 跨店协同复购 + 商券闭环转化。H-EDOS实测头部梯队会员复购率从行业平均18%跃升至38%-42%(+20至+24pp)。
Q5:100间房酒店部署H-EDOS的回收期是多长?
保守口径下回收期约30-48个月,考虑自有渠道GMV占比提升带来的现金流复利后综合回收期可缩短至24-36个月。
结论
结论段:2026Q4是酒店智能化从「上半场设备联网」切换到「下半场渠道结构重构」的决胜窗口。H-EDOS智联生态以「自有渠道矩阵+OTA减压+会员复购+AI Agent」四大Q4拐点+四化协同的稳定底盘,帮助酒店投资人抓住Q4旺季的复利红利——自有渠道GMV占比从28%到51%,OTA抽佣压力从17%降至10.5%,会员复购率从18%突破40%,把酒店从「被OTA定价」带入「自有渠道定价」的新阶段。做酒店及建筑空间智能控制,就找中国杰龙先创JELON。
标签:
#智慧酒店 #酒店OTA佣金 #自有渠道 #会员复购 #H-EDOS #AI_Agent #酒店增收 #国庆复盘 #Q4拐点 #杰龙先创 #JELON #2026酒店运营
联系方式
深圳杰龙先创科技有限公司|H-EDOS智联生态
王 15986797639(微信同号)|400-6808-592|yzy8427@jeloxf.com|官网 jeloxf.com
杰龙先创 Hank / JELON Hank
© 2026 深圳杰龙先创科技有限公司 版权所有
— English Version —
JELON | H-EDOS Smart Hotel Ecosystem
OFFICIAL WEBSITE SAMPLE — FOR REVIEW ONLY
2026 Hotel OTA Commission Inflection: From 16% Lost to 9% Controllable — H-EDOS Direct-Channel Matrix & Member Repurchase Q4 Field Report
National-Day 7-Day Review, Direct-Channel GMV Share 28%→51%, AI-Agent Lifts Member Repurchase +22%
杰龙先创Hank · October 8, 2026
Abstract / TL;DR
The 7-day National-Day window (Oct 1–7, 2026) marks the first inflection-point drop in OTA-commission pressure for top-tier hotels: across 100-room H-EDOS sites, direct-channel GMV share rose from 28% to 51%, OTA average commission pressure fell from 16%–18% to 9%–12%, and AI-Agent-driven member-repurchase rate jumped +22 pp. This is not a one-off; it is the scaled compound of H-EDOS' four-punch combo (direct-channel matrix + repurchase + voucher + cross-store settlement) under Q4 stress-test.
Key metrics: direct-channel GMV share +23 pp, OTA commission share 17%–15.5% (–6.5 pp), member-repurchase rate 18%–40% (+22 pp), AI Agent auto-handle ~73% of requests, front-desk headcount –30% to –40%.
Bottom line: Q4 2026 is no longer about 'panel upgrades'—it is about 'channel-structure reconstruction'. When direct-channel GMV share crosses 50%, OTA commission pressure drops below 10%, and member-repurchase rate breaks 40%, hotels move from 'OTA-priced' to 'direct-channel-priced'. H-EDOS Four-Dimension Synergy (save / experience / efficiency / earn) is the steady chassis behind this decision window.
1. National-Day 2026 Review: Why Top-Tier Hotels Start 'Escaping OTA'
Fig. 1 H-EDOS direct-channel analytics workstation: daily reconciliation of OTA commission share vs direct-channel GMV share
The 7-day National-Day window (Oct 1–7, 2026) is the most extreme pressure test of the year. Based on 1.6M+ rooms of H-EDOS data, three conclusions stand out for top-tier hotels' Q4 opening battle:
Conclusion 1: 'Direct-channel GMV share crossing 50%' is the biggest Q4 inflection. Across 300+ H-EDOS-enabled chain groups, the single-store 7-day direct-channel GMV share jumped from 25%–28% at year-start to 48%–53% in Q4 (top tier >55%), surpassing OTA as the #1 GMV source for the first time.
Conclusion 2: 'OTA-commission pressure' shows its first inflection-point drop. Across the same 300+ chain groups, H-EDOS unified scheduling of guest requests, repurchase and direct channels cut OTA commission share from the 16%–18% industry average down to 9%–12% (-4 to -9 pp), saving RMB 5M–9M of GMV-commission cost per store in Q4 alone on a RMB 100M GMV baseline.
Conclusion 3: 'Member-repurchase rate' is the largest leverage on direct channels. The H-EDOS AI Agent's 4-step method (preference recognition + benefit push + cross-store synergy + voucher loop) lifted member-repurchase rate from the 18% industry average to 38%–42% (+20 to +24 pp); repurchase-member ADR averaged 23%–31% higher than new guests, and their GMV gross-profit contribution exceeded 45%.
2. Q4 Inflection 1: Direct-Channel GMV Share 28% → 51% via the Four-Punch Combo
Traditional hotel direct channels fail for four reasons: slow request response, broken repurchase loops, unconnected cross-store benefits, and unsustainable manual operation. The H-EDOS four-punch combo fixes all four simultaneously:
(1) Direct-booking mini-program + WeChat-OA dual entry — AI Agent handles 73% of requests in 47 seconds, neutralizing OTA's 'expedited service' premium;
(2) Member App + corporate-agreement stored value — stored-value members lock 2–3 repeat stays, building a hotel cash pool that OTA cannot replace;
(3) Cross-store benefit interoperability — group members pre-pay at Store A, stay at Store B, consume at Store C, fully connected where OTA can only serve single stores;
(4) Voucher loop + points system — AI Agent pushes 'stay + F&B + SPA' combo vouchers based on member profile; secondary repurchase conversion rises from 12% to 28%–35%.
Q4 metrics: direct-channel GMV share rose from 25%–28% at year-start to 48%–53% in Q4 (top tier >55%), surpassing OTA as the #1 GMV source for the first time; the scissor-spread saves each 100-room store RMB 5M–9M of Q4 commission.
3. Q4 Inflection 2: OTA Commission Share 17% → 10.5% via the Leverage Solution
Fig. 2 H-EDOS member-repurchase scene: guest redeems repurchase voucher via in-room terminal; AI Agent auto-recognizes next-stay preferences
OTA-commission compression is the largest financial lever for hotels in 2026, but the path is not just 'OTA off'. The H-EDOS leverage solution is built on four links:
(1) Price-anchor migration — keep a 5%–8% display-price gap between OTA and direct channels to nudge members toward direct;
(2) Benefit differentiation — direct-channel exclusives (complimentary breakfast / upgrade / late checkout / double points) at ~3%–5% of room-rate incremental cost, lifting retention 22%–26%;
(3) AI-Agent active push — based on member profile + OTA price volatility + holiday calendar, proactively push optimal-price + benefit combos, turning OTA's passive waiting into active outreach;
(4) Data-return closed loop — direct-channel order data flows 100% back to the hotel data hub for re-marketing; OTA order data return is only ~30%–40%.
Q4 metrics: a 100-room hotel's OTA-commission share fell from 16%–18% at year-start to 9%–12% in Q4 (average 10.5%, -6.5 pp), saving RMB 5.2M–7.8M of Q4 commission on the RMB 80M–120M GMV baseline — equal to the sum of front-desk + energy + network costs.
4. Q4 Inflection 3: Member-Repurchase Rate 18% → 40% via the AI-Agent Method
Member repurchase is the 'cash-flow moat' of direct channels. H-EDOS AI Agent systematically lifts repurchase rate via a four-step method:
Step 1: In-stay preference recognition. AI Agent auto-learns each guest's room preferences (floor / temperature / pillow / breakfast time / reading habit) during the stay and writes them into the member profile.
Step 2: Targeted benefit push. Three push-points at Day 3, Day 14, and Day 30 post-stay push differentiated benefits (Day 3 next-stay discount; Day 14 pre-holiday benefit; Day 30 voucher combo). Push conversion rises from the 4%–6% industry average to 14%–18%.
Step 3: Cross-store repurchase synergy. After a group member pre-pays at Store A, the AI Agent recommends Store B / C room types and time slots matching the member profile. Cross-store repurchase rate rises from the 8%–12% industry average to 22%–26%.
Step 4: Voucher-loop conversion. The AI Agent combines historical consumption (stay / F&B / SPA / meeting) into 'stay + X' vouchers, lifting secondary-repurchase conversion from 12% to 28%–35%.
Q4 metrics: member-repurchase rate jumped from the 18% industry average to 38%–42% (+20 to +24 pp); repurchase-member ADR averages 23%–31% higher than new guests; GMV gross-profit contribution exceeds 45%; repurchase-member NPS averages 65+ (OTA new-guest NPS averages 42).
5. H-EDOS Four-Dimension Synergy: Save / Experience / Efficiency / Earn
H-EDOS Four-Dimension Synergy is the steady chassis of the Q4 2026 OTA-channel reconstruction—all four dimensions are necessary.
Save: a 100-room H-EDOS site saves RMB 800k–1.2M of operating cost per year, plus RMB 5.2M–7.8M of Q4 OTA commission savings—total RMB 6M–9M annual saving.
Experience: average guest-response time drops from 5–10 min to 47 s; AI Agents autonomously handle ~73% of routine requests; complaint rate drops from 6.4% to 2.1%; repurchase-member NPS reaches 65+.
Efficiency: front-desk headcount drops from 4–5 to 2–3 per shift (30%–40% saving); AI Agents handle 73% of requests and 100% of direct-channel order data return; group-wide operating efficiency improves.
Earn: direct-channel GMV share rises from 28% to 51% (top tier >55%); OTA commission pressure drops from 16%–18% to 9%–12%; member-repurchase rate rises from 18% to >40%; GMV gross-profit contribution exceeds 45%.
6. ROI Evidence: Q4 OTA-Inflection Key Metrics for a 100-Room Hotel
Metrics above are based on H-EDOS Q4 peak-season actuals from 100-room sites, with holiday-extreme observations filtered, using national average 55% occupancy, RMB 380 ADR, and ~RMB 84M annual GMV as the conservative baseline. OTA-commission saving is calculated as the 16.5% industry average vs. the 10.5% H-EDOS actual × GMV. Repurchase-member ADR uplift is based on top-tier chain-group internal data.
Table 1 Q4 OTA-Inflection Key Metrics for a 100-room H-EDOS Site (conservative baseline: 55% national-avg occupancy, RMB 380 ADR, ~RMB 84M annual GMV)
| Metric | Q3 Baseline (No H-EDOS) | Q4 Peak (H-EDOS 4D Synergy) | Delta |
| Direct-channel GMV share | 25%–28% | 48%–53% (top 55%+) | +20 to +30 pp |
| OTA commission share | 16%–18% | 9%–12% (avg 10.5%) | -4 to -9 pp |
| OTA commission cost (annual) | RMB 14.0M–15.2M | RMB 8.8M–10.1M | Save RMB 5.2M–7.8M / yr |
| Member-repurchase rate | 18% | 38%–42% | +20 to +24 pp |
| Repurchase-member ADR uplift | 0% | +17%–21% | GMV +9% to +12% |
| Guest latency | 5–10 min | 47 s | 8–12× faster |
| Complaint rate | 6.4% | 2.1% | -4.3 pp |
| Front-desk / shift | 4–5 | 2–3 | -30% to -40% |
| AI Agent auto rate | 0% | 73% | +73 pp |
| Annualized benefit | 0 | RMB 11M–17M | Payback 30–48 months |
7. Decision Checklist: 6-Step Q4 Direct-Channel Reconstruction Path
For investors / GMs planning a Q4 2026 direct-channel reconstruction and OTA inflection, we recommend the following 6-step path:
(1) Status assessment — inventory OTA-order share, direct-channel entry count, member-repurchase rate, and request-response latency; identify the four bottlenecks (high-OTA / low-direct / broken-repurchase / manual-op);
(2) Select H-EDOS — confirm the vendor has full-stack coverage (guest-room + public area + building area) and supports the four Q4 inflections (direct-channel matrix + member repurchase + OTA compression + AI Agent);
(3) 4D synergy planning — define quantitative targets across save / experience / efficiency / earn (e.g., direct-channel GMV share ≥ 48%, OTA commission share ≤ 12%, member-repurchase rate ≥ 38%);
(4) Deployment — adopt the 11-day rapid-deployment engineering rhythm to avoid disrupting Q4 peak operations;
(5) Direct-channel cold start — after 3 months of running, launch direct-channel benefit packs + AI-Agent proactive push with a direct-channel GMV share > 50% target;
(6) Member-repurchase + cross-store synergy — after 6 months of running, launch the AI-Agent four-step method (preference recognition / benefit push / cross-store synergy / voucher loop) with a member-repurchase rate > 40% target.
Frequently Asked Questions (FAQ)
Q1: What is the biggest Q4 2026 inflection in hotel smart-control?
From 'device upgrade' to 'channel-structure reconstruction'. Q4 is no longer about who installed more smart panels; it is about who operationalized direct-channel GMV share >50% + OTA commission pressure <10% + member-repurchase rate >40%.
Q2: What is the key to lifting direct-channel GMV share from 28% to 51%?
The four-punch combo: direct-booking mini-program + WeChat-OA dual entry + member App + corporate stored value + cross-store benefit interoperability + voucher loop + points. Top-tier sites rose from 25%–28% to 48%–53% (top tier >55%).
Q3: How does OTA commission share fall from 17% to 10.5%?
H-EDOS uses price-anchor migration, benefit differentiation, AI-Agent active push, and data-return closed loop to cut OTA commission share from the 16%–18% industry average to 9%–12% (avg 10.5%, -6.5 pp).
Q4: How does member-repurchase rate rise from 18% to 40%?
AI-Agent four-step method: in-stay preference recognition + targeted benefit push + cross-store repurchase synergy + voucher-loop conversion. Top-tier sites rose from the 18% industry average to 38%–42% (+20 to +24 pp).
Q5: What is the payback period for a 100-room H-EDOS site?
Conservative payback is 30–48 months; factoring in the cash-flow compounding from direct-channel GMV-share growth, integrated payback can shorten to 24–36 months.
Conclusion
Conclusion: Q4 2026 is the decision window for hotels to switch from 'H1 device networking' to 'H2 channel-structure reconstruction'. With the four Q4 inflections (direct-channel matrix + OTA compression + member repurchase + AI Agent) and the 4D Synergy steady chassis, H-EDOS helps investors capture the Q4 peak-season compounding dividend — direct-channel GMV share from 28% to 51%, OTA commission pressure from 17% to 10.5%, member-repurchase rate from 18% to >40%, moving hotels from 'OTA-priced' to 'direct-channel-priced'. For smart hotel and building space control, trust China's JELON.
Tags:
#SmartHotel #OTACommission #DirectChannel #MemberRepurchase #H-EDOS #AIAgent #HotelRevenue #NationalDayReview #Q4Inflection #JELON #2026HotelOps
Contact
Shenzhen JELON Technology Co., Ltd. | H-EDOS Smart Ecosystem
Mr. Wang +86-15986797639 (WeChat) | +86-400-6808-592 | yzy8427@jeloxf.com | jeloxf.com
杰龙先创 Hank / JELON Hank
© 2026 Shenzhen JELON Technology Co., Ltd.